Hidden pitfalls of insurance
25 April 2012 Reading: 13 min Views: 9 599
Unpleasant surprises are most often faced by those who insured their car under voluntary insurance (motor CASCO).
Unpleasant surprises are most often encountered by those who have insured their car under a voluntary insurance policy and by those who have taken out a loan to buy a car.
The most important document when concluding an insurance contract is not the insurance policy but the Insurance Rules. In most cases you are not shown this document, even though the "client's signature" field of the policy contains the phrase: "I have read the terms and the Insurance Rules." As a result, you confirm that you have read the insurance rules, although in reality this is not the case.
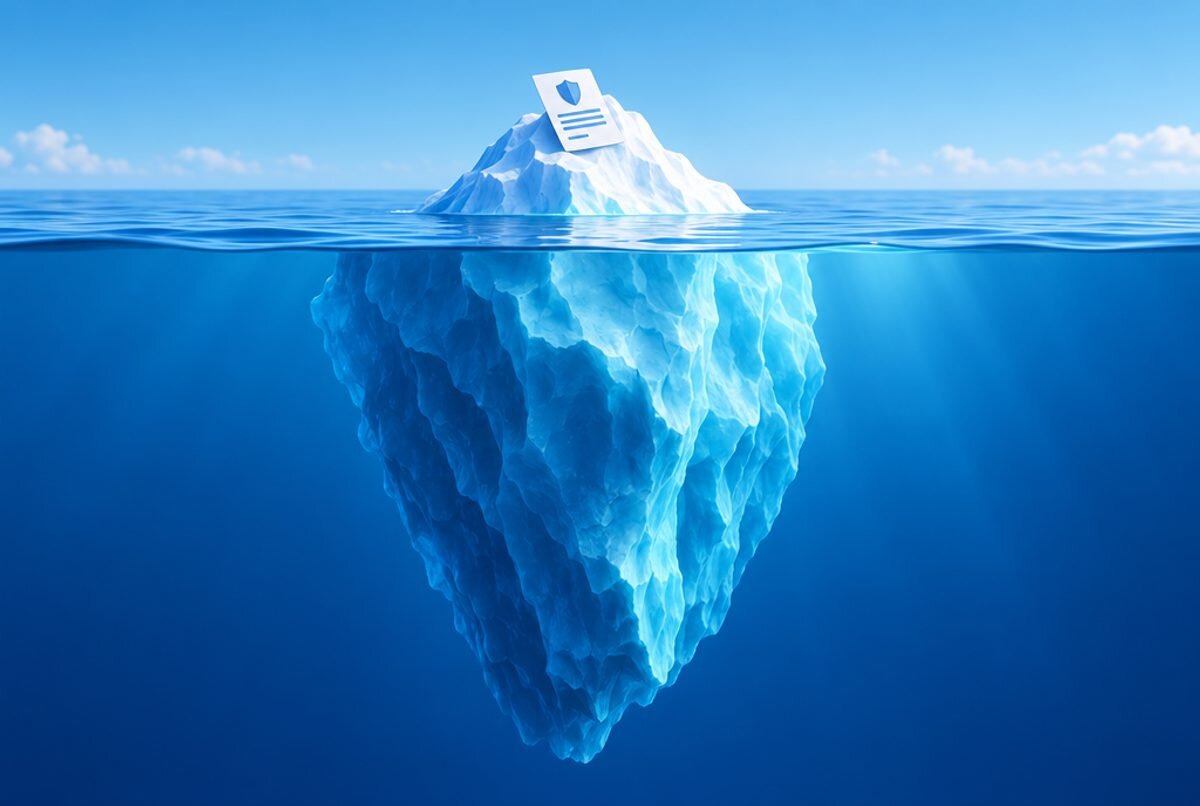
The Insurance Rules are a lengthy document of about 20-40 pages that describes all the insurance terms in great detail. The insurance policy contains only brief extracts from the Insurance Rules. One could say that the insurance policy you receive is just the tip of a large iceberg.
Instead of a policy, an insurance contract may be issued; this is also an acceptable form of relationship between the insurance company and you. Sometimes an insurance contract is issued instead of a policy. It can hold a larger amount of information, but the contract is also prepared on the basis of the Insurance Rules.
Conclusion No. 1. When concluding an insurance contract, it is important to read the Insurance Rules. If the insurance company refuses for any reason to show you the Insurance Rules, decline to conclude the contract. As a last resort, demand that the following phrase be included in the contract or policy: "In the event of a conflict between the terms of this contract (policy) and the Insurance Rules, the provisions of this contract (policy) shall apply."
What do the unfamiliar words mean?
Policies often contain various terms that are not always clear to car owners. Here is a list of such terms:
1. Deductible
The deductible is the unpaid part of the cost of repairing your car. For example, your car is worth 600,000 tenge and you decided to insure it for exactly this amount. The policy issued to you specifies a deductible of 5% of the sum insured. This means that the insurance company will not pay for damage that does not exceed the amount of the deductible.
If the car is damaged by, say, 200,000 tenge, the insurance company will make a payout of 170,000 tenge. The calculation is as follows:
determine the deductible amount: 600,000*5% = 30,000 tenge
calculate the payout amount: 200,000 - 30,000 = 170,000 tenge.
Why is a deductible needed?
A deductible is needed so that, after concluding the insurance contract, the car owner continues to take good care of the car. When a car is insured against any damage (road accidents, theft, carjacking, vandalism, robbery, etc.), there is a risk that the car owner will no longer take proper measures to protect the property. Many begin to think: "Why worry so much now? The insurance company will pay for everything anyway."
To prevent this, the contract provides for a deductible. The general rule is as follows: the insurance company is responsible for the bulk of the losses (85-95%), while the client is responsible for minor damage (5-15%, the deductible).
2. Proportional payout
This condition is usually contained not in the policy itself but in the Insurance Rules. The proportional payout condition is used to protect the interests of the insurance company.
In which cases is a proportional payout applied?
Suppose a car owner decided to save on insurance. To do so, he understated the value of the car, stating that it was worth $15,000 rather than $20,000. This gives the insurance company the opportunity to apply the proportional payout condition. Since the car was not insured for its full value, the payout amount will also be adjusted.
In this example the car was insured for 75% of its actual value; consequently, the payout will be 75% of the damage.
3. Beneficiary
The beneficiary is the person who receives money under the insurance policy. This word takes on special importance when you buy a car on credit. Usually, to obtain a loan, the car must be insured. As a rule, the insurance company is chosen by the bank. You pay for the policy yourself and you are given all the documents, but in the event of an accident the insurance money will be received not by you but by the bank that issued the loan. You will have to find the money for repairing the car on your own.
"That can't be!?" you will say. Look at the "beneficiary" field in your policy: it shows not your name but the name of the bank. Why does the bank do this?
By granting you a loan, the bank bears certain risks. A situation may arise in which the client can neither repay the money (having lost their job and other sources of income) nor return the car to the bank (the car was wrecked in an accident and cannot be restored). In this case the insurance policy will help the bank. It is the insurance company that will protect the bank's interests. For the bank, this is an additional guarantee that the money will be repaid. True, the bank obtains this additional guarantee at your expense, because it is you who pays for the insurance, while the bank (not you) receives the money under the insurance policy.
What else is important to pay attention to when buying an insurance policy?
1. payout deadlines
In the case of compulsory insurance, payout deadlines are regulated by law. If you insure your car voluntarily, each insurance company sets its payout deadlines independently. The total payout period includes:
the period for deciding on the payout itself. Usually from 5 to 20 days. During this time the insurance company "thinks" and decides whether to make the payout or to refuse it, if there are valid reasons for doing so.
the period for the payout itself. It also ranges from 5 to 20 days. During this period the money is actually paid out or transferred to the client's account.
2. the list of documents required for an insurance payout
Voluntary insurance contracts often state, after listing the documents, that "other necessary documents" are also required for the payout. This wording is very vague and therefore convenient for the insurance company. If necessary, it allows the insurance company to "invent" ever new "necessary" documents and thus delay the payout.
It is advisable that the list of documents in the insurance contract be exhaustive and that there be no phrase at all about the need to provide additional documents. Ideally, the contract should contain a special condition stating that the insurance company has no right to require other documents not provided for in the list.
3. the figures in the "actual value" and "sum insured" fields
The "actual value" field shows the market price of your car, while the figure in the "sum insured" field shows the amount for which your car is insured. Let us look at some examples.
Example 1.
"Actual value": 2,000,000 tenge. "Sum insured": 2,000,000 tenge.
This means that the car is insured for its full value. There will be no "surprises" at the time of payout.
Example 2.
"Actual value": 2,000,000 tenge. "Sum insured": 1,200,000 tenge.
This means that the proportional payout condition may be applied. Such situations very often arise with so-called "bank" insurance. When you take out a bank loan, banks try in every way to reduce the cost of obtaining the loan. Therefore, the car is insured not for its full value (2,000,000 tenge) but only for the amount of the loan issued (1,200,000 tenge). On the one hand, this is financially beneficial for the client: you pay less for insurance. On the other hand, in the event of an accident the proportional payout condition applies, meaning that not all of the damage is covered, only part of it.
Example 3.
"Actual value": 2,000,000 tenge. "Sum insured": 300,000 tenge.
This is what so-called "two-sided" insurance usually looks like. As a rule, the proportional payout condition does not apply here, but to be sure of this you need to read the policy and the insurance contract carefully.
4. the wording in the "Refusal of insurance payout" or "Exclusions from insured events" section
Very often, when you insure a car against any damage, you are told that the payout is made in any situation, regardless of whether you are the party at fault or the injured party. In practice, however, it may turn out that these promises are not backed by actual documents.
You need to find the section of the insurance contract or the Insurance Rules that describes the cases in which an insurance payout is refused.
If it contains the wording given below, this means that if you are at fault in a road accident, the insurance company may refuse the payout, even though you were verbally assured of the opposite.
"The insurer has the right to refuse an insurance payout in the event of actions of the policyholder recognised, in accordance with the procedure established by law, as intentional crimes or administrative offences that are in a direct causal relationship with the insured event"
It is advisable to replace this wording, especially if you were given verbal promises of payment in any road accident, regardless of your fault. In this sentence the wording "administrative offences" should be changed to "intentional administrative offences".
Practically any road accident falls under the concept of "administrative offences", which means that, if it wishes, the insurance company can easily refuse the payout if you turn out to be at fault for the accident. By contrast, only a small number of road accidents can be classified as "intentional administrative offences", so cases of refusal will be kept to a minimum.
Conclusion No. 2. To avoid disappointment when receiving a payout, you need to:
read carefully (rather than skim) the insurance policy, the insurance contract and the Insurance Rules; pay particular attention to the following clauses:
- "insured event" (in exactly which situations payment will be made),
- "exclusions from the insured event" (that is, when the payout is not
made),
- "procedure for calculating the insurance payout".
always ask what unfamiliar words mean, such as "deductible" or "proportional payout".
It is also advisable to have the contract reviewed by professionals before signing it.
FREQUENTLY ASKED QUESTIONS.
1. How does the insurance company know how much my car is worth? After all, nobody asks me for documents confirming its value before concluding the contract.
Indeed, when issuing a policy, the insurance company relies on your personal statement. Of course, you can name any amount you like. At the time the contract is concluded, nobody will specifically check it. Questions about the real value of the car will arise only at the time of the insurance payout. If there are doubts about the accuracy of the information you provided, the insurance company will ask an independent appraiser to prepare a report on the actual value of the car at the time the insurance contract was concluded.
If the value of the car turns out to have been understated, the proportional payout condition will be applied. If the value of the car was overstated, the contract will be declared invalid to the extent of the overstatement. In view of this, it is advisable to state the value of the car as accurately as possible when concluding the insurance contract.
2. My friend had the following situation: he was in a road accident; the party at fault had ordinary compulsory insurance, while my friend had expensive voluntary insurance. Since the at-fault party's insurance company assessed only a small amount, my friend also received a payout from his own insurance company. Later, however, his own insurance company sued him and demanded the money back. Is that fair?
The general rule for receiving payouts is this: you can receive money from several companies at once, but the total amount of payouts must not exceed the actual damage. You cannot be paid twice for the same damage. Let us explain this with examples.
Example 1.
A car was damaged to the extent of 1,000,000 tenge, as confirmed by an independent appraiser's report. The car owner received a payout of 700,800 tenge from the at-fault party's insurance company (600 MCI at 1 MCI=1168 tenge) and 900,000 tenge from his own insurance company (less the deductible).
The total amount of payouts was 1,600,800 tenge, which is almost twice the actual damage.
Example 2.
An independent appraiser assessed the damage caused to a car in a road accident at 550,000 tenge. The at-fault party's insurance company carried out its own assessment and agreed to pay 400,000 tenge. The car owner did not want to sue the at-fault party's insurance company and decided to obtain the missing 150,000 tenge under his "two-sided" insurance. Thus, the total amount of payouts did not exceed the actual losses. There is no violation in the actions of the owner of the damaged vehicle.
3. How will my insurance company find out that I received money elsewhere?
One of the conditions for receiving money under voluntary insurance is the right to transfer a recourse claim. This means that before receiving a payout you must sign a document stating that you have transferred all rights to recover the amount paid to your insurance company. Your insurance company can then lawfully recover this amount from the party at fault for the accident or from that party's insurance company. By approaching the party at fault and their insurance company, your insurance company gains full access to all information about the payouts made to you. If it turns out that you received more than you were entitled to (as in Example 1 above), the insurance company will demand that you return this money.
All insurance companies exercise the right of recourse. Recourse claims are usually filed within six months after the payout (the maximum possible filing period is three years). Since the whole truth about the payouts you received will come out anyway, it is better not to mislead your own company, so as not to end up in lengthy court proceedings later.